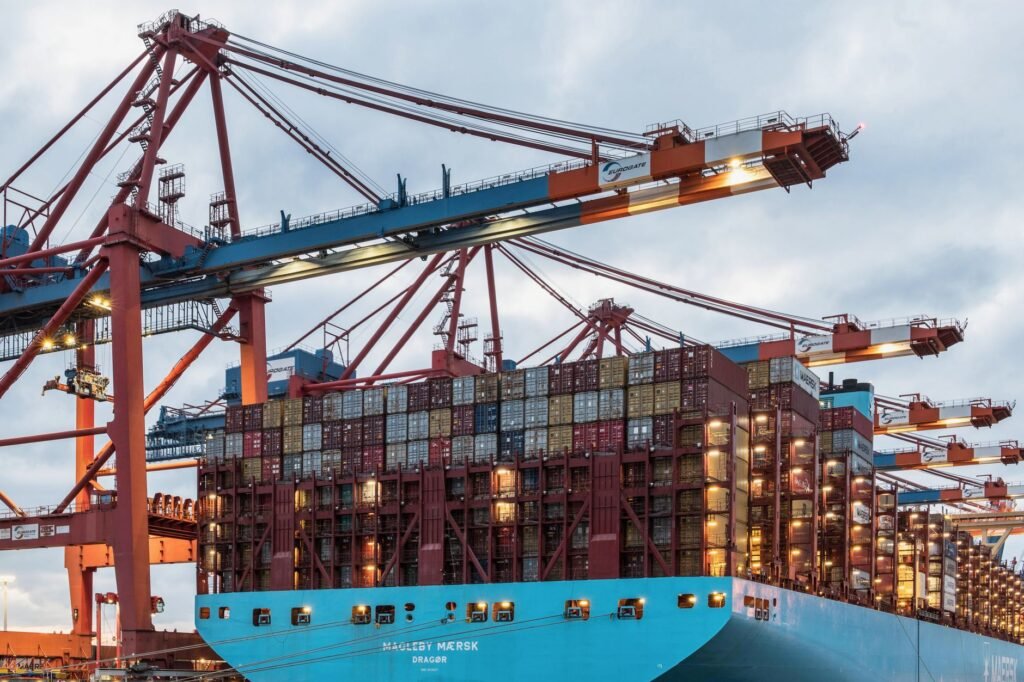
Selling to customers outside the UAE is one of the few cases where VAT is charged at 0% instead of 5%. But the 0% rate is not automatic. It depends on conditions in the law, a strict time limit for goods, and documents that you must be able to show the Federal Tax Authority (FTA) years later. If one condition fails, the sale is treated as if it was made inside the UAE and 5% VAT is due, even if you did not charge it to the customer.
This guide explains how zero-rating works for exports of goods and exports of services. It follows Articles 30 and 31 of the Executive Regulation of Federal Decree-Law No. 8 of 2017 on VAT (Cabinet Decision No. 52 of 2017), as amended by Cabinet Decision No. 100 of 2024 for the export of goods.
Published: 21 October 2026
Quick Answer
- Goods: an export of goods is zero-rated if the goods physically leave the GCC Implementing States, or enter a customs suspension regime, within 90 days of the date of supply, and you keep one of the three accepted sets of evidence.
- Services: an export of services is zero-rated if the customer has no place of residence in an Implementing State and is outside the UAE when the service is performed, and the other conditions of Article 31 are met.
- If you miss the 90 days and the FTA has not extended the period, VAT is charged at the rate that would apply to a supply made in the UAE, which is 5%.
- A move into a Designated Zone is not an export. Goods supplied to or moved into a Designated Zone from the rest of the UAE do not qualify under the export rule.
Why Zero-Rating Matters
A zero-rated supply is still a taxable supply. You charge VAT at 0%, you report the sale in your VAT return, and you can still recover the input VAT on your costs. That is different from an exempt supply, where input VAT is generally blocked. For exporters, zero-rating is what keeps the UAE VAT cost out of the price paid by overseas customers. If you are new to VAT, start with our guide to UAE VAT registration and then return here.
Export of Goods: Two Routes
The Executive Regulation separates exports into two types, based on who arranges the transport.
| Route | Who arranges transport | Who collects the evidence |
|---|---|---|
| Direct export | The supplier, or an agent appointed by the supplier | The supplier (exporter) |
| Indirect export | The overseas customer, or an agent appointed by the customer | The customer or its agent, who must give the supplier a copy |
Direct export
A direct export is zero-rated if two conditions are met:
- The goods are physically exported to a place outside the Implementing States, or are put into a customs suspension regime under the GCC Common Customs Law, within 90 days of the date of supply.
- The exporter retains one of the accepted sets of export evidence (listed below).
Indirect export
An indirect export has the same 90-day requirement, and the export must happen under an arrangement agreed by the supplier and the overseas customer at or before the date of supply. In addition:
- The overseas customer, or its agent, must obtain the evidence and give the supplier a copy.
- The goods must not be used or altered between supply and export, except as needed to prepare them for export or customs suspension.
- The goods must not leave the UAE in the possession of a passenger or crew member of an aircraft or ship.
An overseas customer is a recipient that has no place of establishment or fixed establishment in the UAE and does not reside in the UAE. This is why an invoice to a customer with a UAE branch or UAE-resident agent needs careful checking before you apply 0%.
Sales to departing passengers
The regulation treats a supply of goods in a departure area of an airport or port to a passenger as an indirect export, but only if the goods are meant to leave in the passenger’s possession and the supplier has obtained and kept evidence, such as boarding pass details, that the passenger is travelling to a destination outside the Implementing States. Tourist shopping refunds are a separate scheme, covered in our article on the UAE VAT tourist refund scheme.
The Three Accepted Sets of Export Evidence
Since the amendment made by Cabinet Decision No. 100 of 2024, the exporter (or the overseas customer in an indirect export) must hold any one of these:
- A customs declaration and commercial evidence that proves the export.
- A shipping certificate and official evidence that prove the export.
- A customs declaration that proves the customs suspension arrangement, where the goods were put into customs suspension.
The terms are defined in the regulation:
| Term | Meaning |
|---|---|
| Official evidence | An export certificate or clearance certificate issued by UAE customs or competent authorities, or a document certified by the authorities of the destination country stating that the goods entered that country |
| Commercial evidence | A document from a sea, air or land transport company or agent proving departure of the goods: air waybill or manifest, sea waybill or manifest, or land waybill or manifest |
| Shipping certificate | A certificate from a transport company or agent that stands in for commercial evidence when it is not available |
Whatever evidence you hold must identify the supplier, the consignor, the goods, the value, the export destination, and the mode of transport and route. A transport document that names the wrong consignor or does not match the invoice value is a weak document in an audit.
The FTA may refuse documents that do not sufficiently prove the goods left the UAE, and may specify alternative forms of evidence depending on the nature of the export or the goods.
The 90-Day Rule in Practice
The 90 days run from the date of supply. The date of supply is set by the time-of-supply rules in the VAT law, so confirm it for each sale rather than assuming it is the invoice date. Our guide to tax invoices and credit notes explains how invoice timing interacts with the date of supply.
If you cannot export within 90 days, you can apply in writing to the FTA for an extension. The FTA may grant it only in two cases:
- Circumstances beyond the control of the supplier and the recipient have prevented, or will prevent, export within 90 days.
- Because of the nature of the supply, it is not practicable to export the goods, or a class of goods, within 90 days.
Apply before the deadline passes, not after. If the goods are not exported within 90 days, or within any longer period the FTA allowed, VAT is due at the UAE rate on the original supply. Practically, this means you must correct the VAT position in the return for the period in which the deadline lapsed, and you may need to recover the VAT from the customer under your contract.
There is one more protection in the regulation. A supply stays zero-rated if goods that would have been exported are destroyed or cease to exist in circumstances beyond the control of both the supplier and the recipient.
Export of Services
Services are treated differently because there is no physical border crossing. Article 31 zero-rates an export of services in three situations.
Customer outside the UAE
The service is zero-rated if all of these are true:
- The recipient does not have a place of residence in an Implementing State, and is outside the UAE at the time the service is performed.
- The service is not directly connected with real estate in the UAE, any improvement to it, or movable assets located in the UAE at the time the service is performed.
- The service is not treated as performed in the UAE or in a Designated Zone under the place-of-supply rules in the Decree-Law.
A person is considered “outside the State” if their presence in the UAE is less than 30 days and is not effectively connected with the supply.
Services performed outside the Implementing States
A service that is actually performed outside the Implementing States, or the arranging of such a service, is also zero-rated.
Outbound tour packages
The facilitation of outbound tour packages is zero-rated for the part of the service that relates to the tourism products outside the Implementing States.
The anti-abuse exception
The regulation removes zero-rating where a service is provided under an agreement with a non-resident recipient, if the service is, or is reasonably foreseeable to be, received in the UAE by another person (for example an employee or director of the non-resident), and it is reasonably foreseeable at the time of the agreement that this person will receive services for which input tax is not fully recoverable. Group service arrangements with UAE staff of an overseas parent are the usual place where this arises.
Free Zones, Designated Zones and the GCC
Three zone concepts are often confused:
- Free zone company: a legal category. Being in a free zone does not by itself make a supply an export.
- Designated Zone: a specific geographic area listed by Cabinet Decision, treated as outside the UAE for certain goods supplies. Moving goods into one from the rest of the UAE is not an export. See our list of VAT Designated Zones and our note on the free zone VAT position.
- Implementing States: the GCC states that have implemented VAT. The export rule requires goods to leave all Implementing States, so a sale delivered to another GCC state that has implemented VAT is not an export in this sense and follows the rules for GCC supplies. Customs treatment on entry is covered in our article on UAE customs duty.
Common Export VAT Errors
| Error | Why it matters | Fix |
|---|---|---|
| Zero-rating a sale delivered to a Designated Zone | A movement into a Designated Zone is not an export | Check the delivery address against the Designated Zone list |
| No export evidence on file | Zero-rating can be refused | Keep one full set of evidence per shipment, linked to the invoice number |
| Evidence names a different consignor or value | Fails the identification requirement | Match the transport document to the invoice |
| 90 days passed with no extension | VAT due at the UAE rate | Track open shipments and apply for an extension in writing before expiry |
| Customer collected goods but left in a passenger’s baggage | Indirect export conditions fail | Document the shipping method before releasing the goods |
| Services zero-rated for a customer physically present in the UAE | Customer not outside the UAE at the time | Record where the customer was when the service was performed |
| Customer has UAE residence or branch | Not an overseas customer | Check the customer’s registration and establishment |
A Simple Monthly Export Control
- List every zero-rated invoice issued in the month.
- Mark the date of supply and the 90-day deadline for goods.
- Match each shipment to its evidence set and confirm the six identification details.
- For services, record the customer’s location and residence, and check for UAE real estate or asset links.
- Chase open shipments at day 60 and decide whether an extension request is needed.
- Before filing the return, confirm that zero-rated sales in the return agree with this list. See our VAT return filing guide.
Record Keeping
Keep the invoice, contract, transport documents, customs documents and correspondence for every zero-rated export for the full VAT retention period. Our guide on UAE corporate tax record keeping explains why many businesses keep everything for seven years.
Frequently Asked Questions
Is an export from the UAE always zero-rated?
No. Goods must leave the Implementing States, or enter customs suspension, within 90 days of supply and you must hold the required evidence. Services must meet the Article 31 conditions.
How long do I have to export goods to keep the 0% rate?
90 days from the date of supply, unless the FTA has granted an extension after a written application.
What happens if I miss the 90 days?
VAT is charged at the rate that would have applied if the supply was made in the UAE, which is 5%.
What export evidence do I need?
One of three sets: customs declaration plus commercial evidence; shipping certificate plus official evidence; or a customs declaration proving a customs suspension arrangement. The documents must identify the supplier, consignor, goods, value, destination, and mode of transport and route.
Can the FTA extend the 90-day period?
Yes, after a written application, if events beyond the control of the supplier and recipient prevent export, or if the nature of the supply makes export within 90 days impracticable.
Is a sale to a Designated Zone an export?
No. A supply of goods to a Designated Zone, or a movement of goods into one from the rest of the UAE, is not treated as an export.
Is a sale to another GCC country zero-rated as an export?
The export rule requires goods to leave the Implementing States. Deliveries to other GCC states that have implemented VAT follow separate rules, so check before applying 0%.
Are services to a foreign customer zero-rated?
They can be, if the customer has no place of residence in an Implementing State, is outside the UAE when the service is performed, and the service is not tied to UAE real estate or movable assets and is not treated as performed in the UAE under the place-of-supply rules.
Can I recover input VAT on costs linked to zero-rated exports?
Yes. Zero-rated supplies are taxable supplies, so input VAT linked to them is generally recoverable, subject to the normal rules on valid tax invoices. See input tax apportionment.
Does a customer who collects goods and carries them out as hand luggage count as an export?
Not under the indirect export rule. The goods must not leave the UAE in the possession of a passenger or crew member, apart from the specific departure-area sales described above.
Related Reading
- Juvenile Work Permit in the UAE 2026: Rules for Employing Workers Aged 15 to 18 (Yalah Dubai)
- UAE VAT Tax Invoices and Credit Notes 2026
- UAE Reverse Charge Mechanism 2026
- Common VAT Mistakes in the UAE
- UAE VAT Return Filing 2026: Complete Guide
- UAE Import VAT and Customs Declarations 2026
Need Help Reviewing Your Export VAT?
If you want a second pair of eyes on your zero-rated sales, your export evidence files or your 90-day tracking, Qaspro Global can review a sample and tell you what to fix before the FTA does. Message us on WhatsApp at +971 55 153 9679.
This article is general information based on Articles 30 and 31 of the Executive Regulation of Federal Decree-Law No. 8 of 2017 as available on the FTA and Ministry of Finance websites on 21 October 2026. It is not tax advice for your specific facts. Check current rules at tax.gov.ae.
Founder & CEO, Qaspro Global — UAE tax expert with 16+ years of experience in VAT, corporate tax and FTA audit support.