Published: 6 September 2026
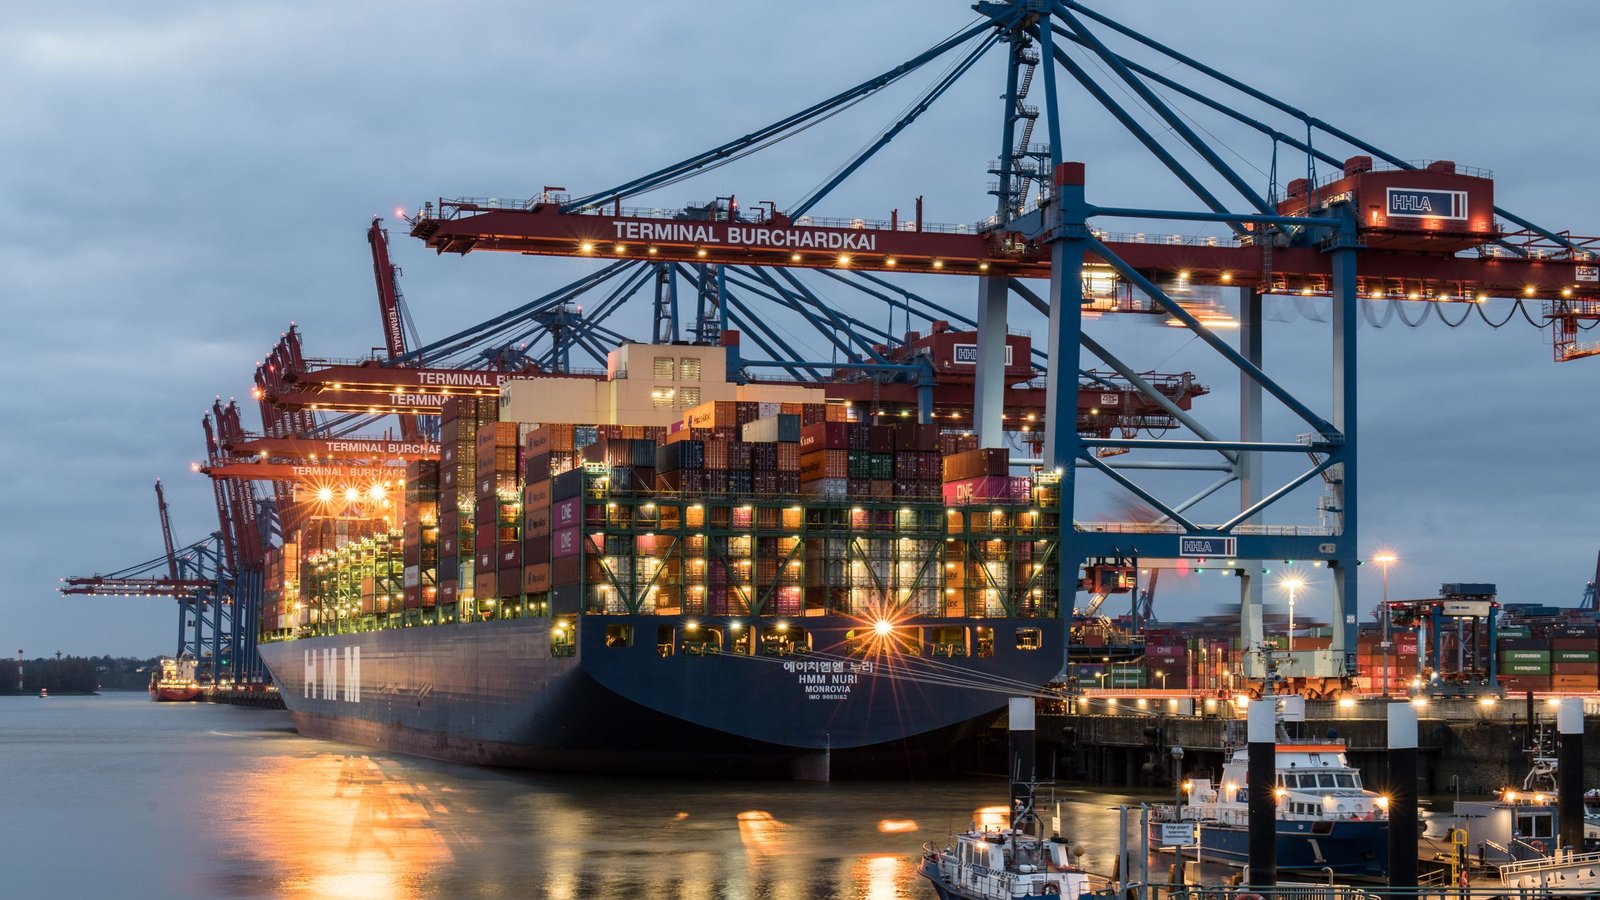
If your UAE business imports goods, two separate government charges land on that shipment before it clears the port: customs duty and import VAT. They are not the same thing, they are not calculated the same way, and they are not treated the same way on your Corporate Tax return. Getting the two confused is one of the most common bookkeeping mistakes we see in import-heavy businesses, and it usually shows up months later as a messy reconciliation between the customs declaration, the VAT return, and the Corporate Tax computation.
This guide sets out how UAE customs duty actually works in 2026: the standard rate, the goods that are exempt or taxed higher, how free zone companies avoid paying duty until goods enter the mainland, and, the part most guides skip, exactly how customs duty and import VAT are treated when you calculate your UAE Corporate Tax liability.
Quick Answer
UAE customs duty is charged at a standard rate of 5% of the CIF value (Cost, Insurance, and Freight) of imported goods, under the GCC Common Customs Law administered by the Federal Customs Authority (FCA). Tobacco products carry a 100% duty and alcohol carries 50%, while essential goods such as fresh food, grains, and certain medical supplies and books are duty-free. Goods held inside a UAE free zone are not subject to customs duty until they move into the mainland or another GCC state, and re-export to a destination outside the GCC is duty-free. For Corporate Tax purposes, customs duty is a non-recoverable cost that is generally deductible as part of the cost of goods, while import VAT under the reverse charge mechanism is normally a net-neutral, self-assessed tax that does not itself create a Corporate Tax deduction unless it becomes irrecoverable.
What Is UAE Customs Duty and Who Charges It
Customs duty in the UAE is governed by the GCC Common Customs Law, a unified framework applied across all six Gulf Cooperation Council states. At the federal level, the Federal Customs Authority (FCA) sets policy, negotiates international trade agreements, and oversees the application of the GCC Common Customs Tariff. Day-to-day clearance and duty collection is handled by each emirate’s own customs administration, Dubai Customs, Abu Dhabi Customs, Sharjah Customs, and the others, each operating its own electronic clearance portal (Dubai Trade for Dubai-origin shipments, for example) while applying the same federal tariff and procedure rules.
This two-layer structure matters practically: the rate and the exemption categories are set at the federal/GCC level and apply uniformly, but the actual declaration, inspection, and payment process runs through whichever emirate’s customs system your shipment enters through.
The Standard 5% Rate and Higher-Rate Categories
For most goods, UAE customs duty is charged at 5% of the CIF value, the cost of the goods themselves, plus insurance, plus freight to the UAE port of entry. This is the rate that applies to the overwhelming majority of commercial imports: electronics, machinery, furniture, textiles, general merchandise, and raw materials.
A short list of goods carries a materially higher rate:
| Goods category | Customs duty rate |
|---|---|
| Most general goods | 5% of CIF value |
| Alcohol | 50% of CIF value |
| Tobacco products | 100% of CIF value |
| Essential foods (rice, sugar, meat, grains) | 0% (duty-free) |
| Certain medical supplies and pharmaceuticals | 0% (duty-free) |
| Printed books | 0% (duty-free) |
Tobacco and certain sweetened or energy products can also carry UAE Excise Tax on top of customs duty, a separate charge covered in our UAE Excise Tax rates guide. Importers of these categories need to account for customs duty, excise tax, and import VAT as three distinct charges, calculated in sequence, not one combined figure.
HS Code Classification: Where Importers Actually Get Tripped Up
Every imported item must be classified under a Harmonized System (HS) code, which determines the applicable duty rate, whether an item qualifies for an exemption, and whether it needs an additional permit (food, medical devices, chemicals, and telecoms equipment all carry extra approval requirements from other UAE authorities alongside customs).
As of 2026, the UAE requires 12-digit HS codes for customs declarations, up from the shorter codes some importers were still using. A misclassified or outdated HS code is one of the most common causes of shipment delays: an incorrect code can trigger a “Customs Suspense” status that holds the shipment at port while the classification is queried, sometimes for several days. If your business imports the same category of goods regularly, it is worth having your broker or customs agent confirm the correct current 12-digit code rather than reusing a code from an earlier shipment.
Free Zone Treatment: Suspension, Not Exemption
One of the most misunderstood points in UAE customs is what actually happens to goods imported into a free zone. The common shorthand “free zones don’t pay customs duty” is only half true, and the distinction matters for cash flow planning.
Under the GCC Common Customs Law, goods brought into a UAE free zone are treated as being outside the customs territory of the UAE for duty purposes. This means:
- While goods sit inside the free zone, customs duty is suspended, not permanently waived. The goods remain under customs control.
- If the goods are re-exported from the free zone to a destination outside the UAE and outside the GCC, no customs duty becomes payable at all, the suspension effectively becomes a permanent exemption for that shipment.
- The moment goods move from the free zone into UAE mainland (or into another GCC state), the standard 5% duty (or the applicable higher rate) becomes payable at that point, calculated on the CIF value.
This is why free zone companies that both import and sell into the mainland need to track, shipment by shipment, which goods have already crossed into the mainland (duty paid) and which remain in free zone status (duty suspended). Moving goods out of a free zone without completing the correct customs declaration is treated as smuggling under the GCC Common Customs Law, with serious penalties, this is not an area where informal shortcuts are safe.
For businesses actually deciding where to set up an import or trading operation, our comparison of mainland versus free zone in Dubai and the Corporate Tax angle on that same decision cover the broader setup considerations beyond customs alone.
Re-Export and Temporary Admission
Two related mechanisms are worth understanding if your business regularly moves goods through the UAE rather than selling them locally:
Re-export from a free zone: goods that entered a free zone and are shipped onward to a destination outside the GCC are exempt from UAE customs duty, provided the re-export is properly declared and documented through the customs system. This is the mechanism that makes UAE free zones attractive as regional distribution hubs.
Import for re-export (mainland route): if goods are imported outside a free zone with the specific intention of re-exporting them, either wholly or partially, the importer can secure a deposit or bank guarantee equal to the customs duty amount instead of paying the duty upfront. This declaration type currently applies to shipments valued above AED 20,000 (with an exception for vehicles), and the deposit is released once the re-export is confirmed.
Temporary admission: goods brought into the UAE temporarily, for exhibitions, repair, testing, or processing before being re-exported, can also qualify for duty suspension under specific temporary admission procedures, provided the intended re-export and timeline are declared upfront.
In every case, the exemption or deferral depends on correct, upfront declaration. Customs duty that should have been paid does not simply disappear if the paperwork was wrong; it becomes a liability that can be assessed later with penalties attached.
How Customs Duty Interacts With VAT
Customs duty and import VAT are charged on the same shipment but work completely differently, and this is where we see the most confusion in client bookkeeping.
Customs duty is paid (or suspended/exempted, per the rules above) at the point of import, based on the CIF value. It is not a recoverable tax, once paid, a business cannot claim it back the way it claims back input VAT. It becomes a real, embedded cost of the goods.
Import VAT, by contrast, is charged under the reverse charge mechanism. A UAE VAT-registered business importing goods does not pay VAT to a foreign supplier at the point of sale; instead, it self-accounts for VAT at the standard 5% rate on its own VAT return, calculated on the customs value of the goods (which includes the CIF value plus the customs duty itself). For a fully taxable business making only standard-rated supplies, this reverse-charge VAT is typically net-neutral: the same amount is declared as output tax and reclaimed as input tax on the same return, so no cash changes hands with the Federal Tax Authority (FTA) on a properly reconciled import.
As of 1 January 2026, VAT-registered importers are no longer required to issue a formal self-invoice for reverse-charge imports, but the FTA still expects robust digital records, the customs declaration, supplier invoice, and proof of value, to support the VAT treatment on audit.
Import VAT recovery is not automatic in every case. Recovery can be blocked, in whole or in part, where:
- The business makes exempt supplies (so the goods relate partly to non-recoverable activity).
- The import is partly for non-business or personal use.
- The importer of record on the customs declaration does not match the VAT-registered entity claiming recovery.
- Documentation is incomplete or the VAT return does not reconcile with the customs records.
Where import VAT becomes genuinely irrecoverable for one of these reasons, it stops being a pass-through tax and becomes a real cost, which is the point at which it starts to matter for Corporate Tax deductibility too, discussed below. For the mechanics of the reverse charge more broadly, see our guide on VAT registration in the UAE.
How Customs Duty Affects Your Corporate Tax Position
This is the part general customs guides tend to skip, and it is the reason we are covering this topic from an accounting angle rather than a logistics one.
Customs duty as a deductible expense: because customs duty is a genuine, non-recoverable cost (unlike VAT, it cannot be claimed back from the FTA), it is generally treated as part of the landed cost of the imported goods, folded into cost of goods sold or inventory cost, rather than sitting as a separate tax line. Under the UAE Corporate Tax Law (Federal Decree-Law No. 47 of 2022), ordinary and necessary business expenses, including the cost of goods sold, are deductible in calculating taxable income, provided they meet the general deductibility conditions (wholly and exclusively for business purposes, properly documented, and not on the law’s specific list of non-deductible items). Customs duty paid on trading stock or inputs used in the business therefore normally reduces taxable profit through the cost of sales, the same way any other direct cost of inventory would.
Import VAT and Corporate Tax: because a fully recoverable reverse-charge VAT amount nets to zero on the VAT return, it typically has no separate impact on the Corporate Tax computation, it is not an expense at all in the accounting sense, just a self-assessed tax that is claimed back in the same period. However, where import VAT becomes irrecoverable (exempt-use goods, non-business use, or a documentation failure that blocks the input tax claim), that irrecoverable portion becomes a real cost in the accounts, and, like any other properly incurred business cost, it can then factor into the Corporate Tax deduction analysis for that expense.
Practical takeaway: keep customs duty and import VAT in separate ledger accounts, reconcile the customs declaration value against both your VAT return and your Corporate Tax cost-of-sales figure every filing period, and flag any irrecoverable import VAT immediately rather than letting it sit misclassified until year-end. For the broader deductibility rules that apply to business costs generally, see our guide on deductible expenses under UAE Corporate Tax.
Free Trade Agreement Preferential Rates
The UAE has Free Trade Agreements (or Comprehensive Economic Partnership Agreements) with a growing number of trading partners, including India, Indonesia, and Israel among others. Goods originating from an FTA partner country can qualify for a reduced or fully exempted customs duty rate, but this is not automatic, the importer must:
- Present a valid Certificate of Origin issued by the exporting country’s authorised body.
- Confirm the goods’ HS code falls within the specific product list covered by that FTA.
- Meet the FTA’s rules of origin (confirming the goods genuinely originate from, or were substantially transformed in, the partner country).
Businesses that import regularly from an FTA partner country should check current eligibility before assuming the preferential rate applies, product coverage and rules of origin vary by agreement and can change.
Step-by-Step: What Happens When Goods Arrive
| Step | What happens |
|---|---|
| 1 | Shipment arrives; importer or customs broker submits the customs declaration with the correct 12-digit HS code |
| 2 | Customs authority assesses CIF value and applies the applicable duty rate (5% standard, or the relevant exemption/higher rate) |
| 3 | Duty is paid (or suspended if entering a free zone, or secured by deposit if for re-export) |
| 4 | VAT-registered importer self-accounts for import VAT under the reverse charge on their next VAT return |
| 5 | Goods are released for entry into the mainland, or held in free zone/bonded status |
| 6 | Customs duty is recorded as a cost of goods; import VAT is reconciled on the VAT return; both are matched against the Corporate Tax cost-of-sales figure at year-end |
Frequently Asked Questions
What is the standard customs duty rate in the UAE?
5% of the CIF value (cost, insurance, and freight) for most goods, under the GCC Common Customs Law.
Do free zone companies pay customs duty?
Not while goods remain inside the free zone, duty is suspended, not waived. Duty becomes payable once goods move from the free zone into UAE mainland or another GCC state. Re-export outside the GCC remains duty-free.
Can I recover customs duty the way I recover VAT?
No. Customs duty is not a recoverable tax. It is a real, embedded cost that is generally deductible for Corporate Tax purposes as part of the cost of the goods, but it cannot be claimed back from the Federal Tax Authority the way input VAT can.
Is import VAT the same as customs duty?
No. Customs duty is charged on the CIF value at import and is non-recoverable. Import VAT is charged under the reverse charge mechanism at 5% on the customs value (including duty), and is normally recoverable as input tax for a fully taxable, VAT-registered business, making it net-neutral.
Does customs duty reduce my Corporate Tax bill?
Indirectly, yes, it increases the cost of goods sold, which reduces taxable profit, provided the general deductibility conditions under the UAE Corporate Tax Law are met.
What happens if my import VAT becomes irrecoverable?
If input VAT recovery is blocked (for example, because the goods relate to exempt supplies or documentation is incomplete), the irrecoverable VAT becomes a real cost in your accounts and can then be relevant to your Corporate Tax deduction analysis, unlike normally-recoverable reverse-charge VAT.
What goods are exempt from UAE customs duty?
Essential foods such as rice, sugar, grains, and meat; certain medical supplies and pharmaceuticals; printed books; and goods covered by specific GCC tariff exemptions or qualifying Free Trade Agreement origin.
What is the customs duty rate on alcohol and tobacco?
Alcohol is charged at 50% of CIF value and tobacco products at 100% of CIF value, both are also typically subject to Excise Tax on top of customs duty.
Do I need a 12-digit HS code for every import?
Yes, as of 2026 the UAE requires 12-digit HS code classification on customs declarations. An outdated or incorrect code is a common cause of shipment delays.
Can I get a customs duty exemption on goods I plan to re-export?
Yes, through either the free zone re-export mechanism or, for mainland imports intended for re-export, a deposit/guarantee mechanism in place of paying duty upfront, for shipments generally valued above AED 20,000 (except vehicles).
Get Import Tax and Corporate Tax Right Together
Customs duty, import VAT, and Corporate Tax deductibility are three separate calculations that all touch the same shipment. Getting one wrong tends to surface the other two at audit time. If your business imports goods regularly and you want your customs cost treatment reconciled properly against your VAT return and your Corporate Tax filing, contact Qaspro Global on WhatsApp for a review.
Related Reading
- Mainland vs Free Zone Dubai 2026
- Mainland vs Free Zone Tax UAE 2026
- UAE Corporate Tax Deductible Expenses 2026
- UAE VAT Registration 2026: Step-by-Step Guide
Founder & CEO, Qaspro Global — UAE tax expert with 16+ years of experience in VAT, corporate tax and FTA audit support.