Published: 2 November 2026
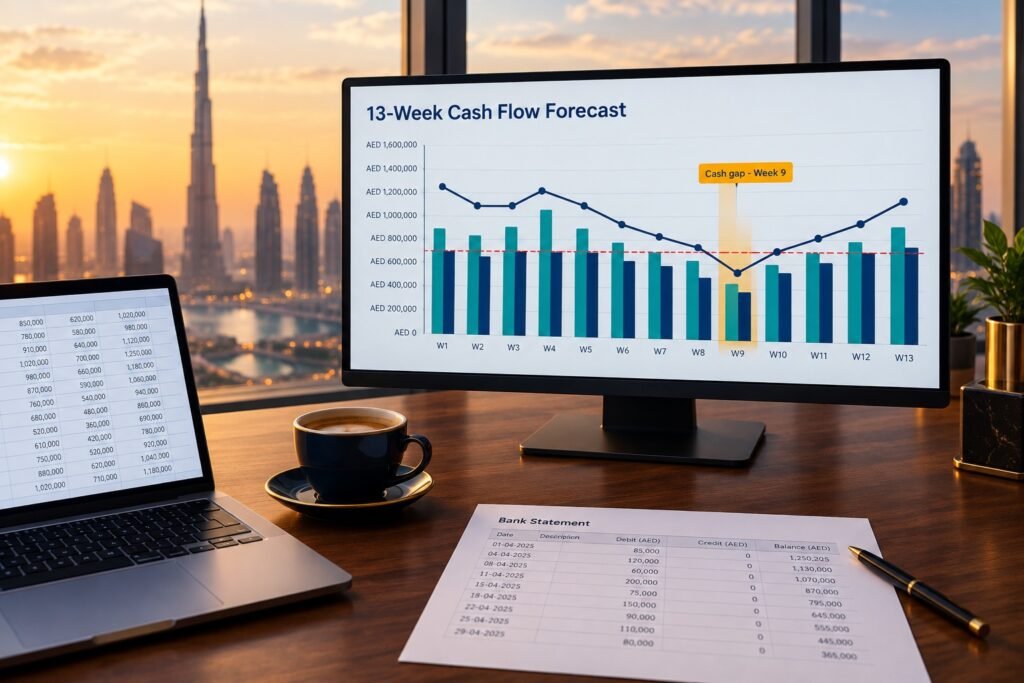
A 13-week cash flow forecast is a week-by-week view of the money you expect to receive and pay over the next three months, refreshed every week. For a UAE business owner, it answers one question that a yearly budget cannot: “Will I have enough cash on the day payroll, rent and suppliers are due?” Automation can now build and refresh this forecast from your live books, while a qualified accountant still decides the assumptions and signs off the result. This is part of our wider guide to AI accounting automation in the UAE.
Most owners we speak to do not have this forecast. They have a bank balance they check on their phone and a feeling about the month ahead. That works until the month a large customer pays late and three supplier bills fall due in the same week. This article explains what a 13-week forecast is, why it is rarely maintained by hand, what automation can take over, what it must not take over, and what it costs to find a cash gap too late.
What Is a 13-Week Cash Flow Forecast?
A 13-week cash flow forecast is a rolling, week-by-week estimate of cash coming in and going out for the next 13 weeks (about one quarter), updated every week so it always looks three months ahead.
Three words matter in that sentence:
- Cash. It tracks money in the bank, not profit. A business can show a profit on paper and still run out of cash because customers have not paid yet.
- Weekly. Cash problems happen on specific days, not on average across a year. Weekly buckets show the exact week a shortfall appears.
- Rolling. Each week the oldest week drops off and a new week 13 is added. The forecast never goes stale because it never ends.
A simple layout has four blocks: opening cash, cash in (customer payments, other receipts), cash out (supplier bills, payroll, rent, loan instalments, other commitments) and closing cash. The closing cash of one week becomes the opening cash of the next. The first week where closing cash goes below your safe minimum is the warning.
Why a 13-Week View Beats a Yearly Budget for Cash Decisions
A yearly budget answers “What do we plan to earn and spend this year?” A 13-week forecast answers “Can we pay what is due, when it is due?” They are different tools.
| Question | Yearly budget | 13-week cash forecast |
|---|---|---|
| Main purpose | Plan targets for the year | Protect cash over the next quarter |
| Time unit | Month or quarter | Week |
| Updated | Once, maybe revised mid-year | Every week |
| Shows a late-paying customer | Rarely | Yes, in the week the cash is now expected |
| Shows a week with too little cash | No | Yes |
| Useful for borrowing, hiring or buying stock decisions | Partly | Directly |
The budget is still useful. But decisions such as “Can we hire next month?”, “Can we pay this supplier early to get a discount?” or “Do we need to talk to the bank now?” depend on cash timing. That is what the 13-week view gives you.
Why Most UAE Owners Do Not Have One Today
We see the same four reasons again and again.
- The spreadsheet was built once and abandoned. Someone builds a good forecast in January. By March nobody has the time to update it, so it quietly stops being true.
- The books are updated weeks late. A forecast built on last month’s unreconciled numbers starts from the wrong opening balance. Every figure after it is wrong too.
- Payment timing is unknown. The forecast needs to know when each invoice will really be paid, not when it is due. That information sits in different places: the sales team, the accounts file, the bank statement.
- Nobody owns it. The owner is busy running the business, and the bookkeeper is busy posting entries. A forecast that belongs to nobody does not get updated.
None of these is a knowledge problem. They are a time and data problem. That is exactly the kind of problem automation is good at.
What Automation Can Take Over
When your accounting records are kept current, software can do the routine, repeatable parts of the forecast every week without anyone opening a spreadsheet. In practical terms, these tasks can move from a person to automation:
- Pulling live bank balances so the opening cash is today’s real figure, not last month’s.
- Reading receivables: which customer invoices are open, their due dates, and how late each customer has paid in the past.
- Reading payables: which supplier bills are coming due and when, so committed outflows appear in the right week.
- Adding recurring items such as payroll, rent, loan instalments and subscriptions on their normal dates.
- Refreshing the forecast every week so the 13-week window rolls forward by itself.
- Flagging a projected shortfall early, for example “closing cash falls below your minimum in week 6.”
- Comparing forecast against actual each week, so you can see how accurate the forecast has been and where it keeps missing.
An owner example, in one line: a distributor with 40 customers and 25 suppliers gets the same weekly cash view that a much larger company would build with a full finance team.
Two things must be true for this to work. First, the underlying books must be current and reconciled; see our guide to bank reconciliation automation in the UAE. Second, the data has to be clean. If duplicate payments or wrong supplier bills sit in the ledger, the forecast repeats those errors. Our article on manual accounting leaks such as duplicate payments, late fees and supplier credits explains how those errors build up.
What Your Qualified Accountant Must Still Decide
Automation is excellent at arithmetic and refresh. It is not responsible for judgement. A forecast is only as good as its assumptions, and assumptions are decisions. These stay with a qualified accountant:
- Assumptions about late payers. The system can show that a customer paid 25 days late on average. The accountant decides whether to forecast the next payment on that pattern, on a better pattern after a phone call, or not at all.
- One-off items. A large equipment purchase, a deposit refund, an insurance renewal or a dispute with a supplier does not follow a pattern. A person must decide whether and when to include it.
- Seasonality. Many UAE businesses have strong and weak periods. The accountant judges which past pattern is a reliable guide and which was unusual.
- Financing choices. If the forecast shows a gap, should you delay a purchase, ask a customer to pay sooner, negotiate with a supplier or arrange funding? That is a business decision with consequences.
- Sign-off and interpretation. Someone qualified must read the forecast, question odd numbers and stand behind it.
The positioning is simple. AI does the routine work. Qualified accountants review and sign off. If a provider tells you the forecast needs no human review, treat that as a warning.
Before and After: Time, Error Risk and Cost
The table below compares a manually maintained forecast with an automated, accountant-reviewed one. The AED figures are a hypothetical illustration, not a measurement and not a quote. They use stated assumptions so you can replace them with your own numbers.
| Item | Before: spreadsheet by hand | After: automated, accountant-reviewed |
|---|---|---|
| Weekly effort to refresh | About 4 hours (collect balances, receivables, payables, retype) | About 1 hour (review and adjust assumptions) |
| Hours per year (52 weeks) | 208 hours | 52 hours |
| Time saved per year | None | 156 hours |
| Typical error risk | Higher: retyped figures, broken formulas, stale opening balance | Lower: figures pulled from the books, with an audit trail |
| How early a cash gap is seen | Often only when the bank balance is already low | Several weeks ahead, in the forecast |
| Illustration: value of time saved | 156 hours at an assumed AED 120 per hour = AED 18,720 per year | Time returned to the owner or finance staff |
Illustration only. Assumptions: 4 hours a week by hand versus 1 hour a week with automation; an assumed internal cost of AED 120 per hour. Your own hours, hourly cost and business size will differ. The figure is not a promise of savings.
The larger benefit is usually not the hours. It is the decision you avoid making on bad information.
The Hidden Cost of Finding a Cash Gap Late
A cash gap found three weeks early is a planning task. The same gap found on the day is a crisis. The costs rarely appear as one line in your accounts, which is why owners underestimate them.
- Late supplier payments. Suppliers may stop extending credit, ask for cash on delivery or move you down their priority list.
- Emergency borrowing. Short-notice funding is usually more expensive and offered on weaker terms than funding arranged in advance.
- Missed early-payment discounts. If a supplier offers a discount for paying early, you can only use it if you know you will have the cash.
- Payroll and WPS stress. Salary payments through the Wages Protection System have fixed dates. Missing them creates problems with staff and with the authorities. Seeing the shortfall early gives you time to act.
- Decisions made on stale data. Hiring, stock purchases or a new lease decided without a forward view of cash can commit money you will not have.
- Owner time. Chasing payments in a hurry takes more time than a calm weekly review.
Illustration (hypothetical, not a measurement): suppose a business discovers in week 3 that week 6 will be short by AED 80,000. With three weeks’ notice it can ask two large customers to pay earlier, move one supplier payment by agreement and avoid emergency funding. With no notice, the same gap may mean a rushed loan, a missed discount and a strained supplier relationship. The gap is the same; the cost is different.
Risks and Controls to Demand From Any Provider
Automation introduces its own risks. A responsible provider should be able to answer each of these plainly.
- Human review. A qualified accountant reviews every forecast and every material assumption. Ask who that person is and how often they review.
- Audit trail. Every number should trace back to a source: a bank line, an invoice or a stated assumption. You should be able to see what changed since last week and why.
- Data security. Your bank balances, customer names and supplier details are sensitive. Ask where the data is stored, who can access it and how access is removed when someone leaves.
- UAE data protection. Ask how the provider handles personal data under the UAE Personal Data Protection Law (Federal Decree-Law No. 45 of 2021). Verify the current position on the official UAE legislation site, as implementing rules continue to develop.
- Who sees the forecast. A cash forecast is confidential. Decide in advance who in the business receives it: owner, finance lead, bank, investors.
- Clear limits. The forecast is an estimate, not a guarantee. A good provider says so and shows how accurate past forecasts were.
- Exit. If you leave, you should be able to take your data and your forecast model with you in a usable format.
Owner Checklist: Questions to Ask Any Provider
Use this list before you agree to anything.
- Are my books kept current and reconciled before the forecast is built?
- Does the forecast start from my real bank balance each week?
- How are expected customer payment dates decided, and who reviews them?
- Who is the qualified accountant that signs off, and what is reviewed each week?
- How will I be told early if cash is projected to fall below my minimum?
- Do I get a weekly comparison of forecast against actual?
- Can I see where each number came from?
- Where is my data stored, and who can see it?
- How does the provider handle personal data under UAE law?
- What happens to my data and forecast if I stop the service?
Where This Fits With Your Other Reports
A cash forecast looks forward. Your other numbers look back or look at today. Together they give a full picture:
- The owner dashboard of five morning numbers tells you where the business stands today.
- A faster month-end close gives you clean figures sooner, which is the starting point for a trustworthy forecast.
- Bank reconciliation automation keeps the opening balance accurate.
- The 13-week forecast tells you what is coming and whether you can afford it.
We do not repeat those articles here. If you want the full picture of what automation can and cannot do for a UAE business, start with the AI accounting automation hub.
Frequently Asked Questions
What is a 13-week cash flow forecast?
It is a week-by-week estimate of cash receipts and payments for the next 13 weeks, updated every week so it always looks one quarter ahead.
Why 13 weeks and not 12 months?
Thirteen weeks is short enough to forecast with reasonable confidence and long enough to act on a problem. Beyond that, customer and supplier timing becomes too uncertain for weekly planning.
Is a cash flow forecast the same as a budget?
No. A budget sets targets for income and spending. A cash forecast predicts the timing of actual money moving in and out of the bank.
Can a profitable business still run out of cash?
Yes. If customers pay late while suppliers, payroll and rent are due on time, a profitable business can have a cash shortfall. The forecast shows it in advance.
What data does an automated forecast need?
Current bank balances, open customer invoices with due dates, open supplier bills with due dates, and recurring commitments such as payroll, rent and loan instalments. The books must be up to date for the output to be reliable.
What can automation not do?
It cannot decide how late a difficult customer will really pay, whether to include a one-off item, how seasonality will play out or how to respond to a shortfall. Those need a qualified accountant and the owner.
How often should the forecast be refreshed?
Weekly. A forecast refreshed monthly misses the timing that makes it useful.
How accurate will it be?
It is an estimate. Accuracy improves when you compare forecast against actual each week and correct the assumptions that keep missing. Ask any provider to show how accurate their past forecasts have been.
Is my financial data safe in an automated forecast?
That depends on the provider. Ask about storage location, access control, audit trail and how personal data is handled under UAE data protection law before you share anything.
Does the forecast replace my accountant?
No. It removes routine work so your accountant can spend time on review, judgement and advice.
Will this work for a small business?
Yes. A small business with a handful of customers and suppliers gains the same weekly warning. The smaller the cash cushion, the more a few weeks’ notice matters.
Talk to Us
If you want to know whether a rolling cash forecast would help your business, message us on WhatsApp and tell us roughly how many customers and suppliers you deal with. Start the conversation at wa.me/971551539679. If running a team also brings visa or labour paperwork questions, our sister company Yalah Dubai explains one common problem in its guide on what to do when a company holds an employee’s passport. You can also read the full AI accounting automation guide first.
Related Reading
- Owner dashboard: 5 numbers every UAE business owner should see each morning
- Month-end close in 2 days instead of 10
- Bank reconciliation automation in the UAE
- Manual accounting leaks: duplicate payments, late fees and supplier credits
- AI accounting automation in the UAE
- Company holding your passport in the UAE (Yalah Dubai)
Founder & CEO, Qaspro Global — UAE tax expert with 16+ years of experience in VAT, corporate tax and FTA audit support.